I’ve spent the last week doing something I should have done ages ago: building tools to make your life easier. They’re here. now. I think they are great (but then I am biased).
They are still in beta, so if you find any bugs please let me know. Let’s meet them:
AskITM - Your AI Companion
ITM’s very own AI, trained on the latest book (the Challenge Edition, not yet published) results and all previous blogs. It’s sitting in the corner of the site right now – click it, ask it anything about the ITM Plan, and get an answer right away. (More on how it’s trained, and its limits, in a minute.)
ITM Calculators
Instead of you having to ask if your calculations are correct and wait for a response – now you get it instantly! Meet:
Time Value Calculator– plug in the price, strike, and premium, get an instant answer on whether it’s under the Base or Turbo threshold
Roll-Up Checker– tells you exactly when your strike’s drifted too far and it’s time to roll.
White Space Checker – confirms whether a golden or death cross has actually cleared the threshold, or is just touching it.
Bear Signal Checklist– four conditions, one clear verdict, no more juggling them in your head.
They’re all sitting under the new Calculators menu. Bookmark it.
ITM Replication Pack
After many requests for access to my backtesting and source data – and here it is: the Replication Pack. It has everything you need to run your own backtesting and check my results. Every rule, every trade, every number.
I have overhauled the ‘swansong’ edition published earlier this year, including updating all the results to 30 June 2026. There is no difference in the execution of the bull-market or bear-market strategies, but I have refined and updated the text. I am planning to launch the new edition in two weeks.
I have always said ‘don’t believe me – check for yourself’ – and that will be the theme of the Challenge Edition. Readers will be referred to the Replication Pack to test for themselves. And if they can get a better result, I want to hear about it!
A few more things about AskITM
It’s trained on the new ITM Challenge Edition, not the currently published book. If you ask it about a specific page number or figure, it’s working from the updated manuscript – so don’t be surprised if it doesn’t match your copy. The Challenge Edition isn’t for sale yet, but the numbers and methodology it’s answering from are the current, correct ones.
It only knows what I’ve actually written. I’ve been very strict about this: derive your answers from my articles and books, don’t guess. It won’t reach for general internet wisdom about options trading, and if something’s outside what I’ve published, it’ll say so honestly rather than make something up.
Ask it anything about the ITM Plan, the Base or Turbo Models, or how to use the Replication Pack. If you manage to stump it, that’s useful to know too.
If you find an answer that you think is a bit dodgy please let me know – happy for feedback, I want to make sure it is perfect.
To the markets . . .
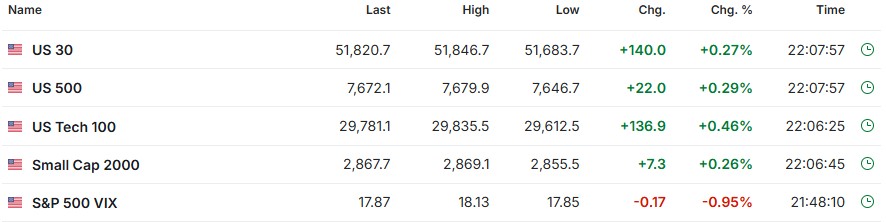
Now that the uncertainty over the Fed decision is over (and they did exactly what everyone was expecting) we may see some movement. I notice that the volume has picked up slightly so that may be a good sign. All the indicators on the economy seem good – apart from inflation (when did it start being described as ‘sticky’? seems an odd use of words.) Hopefully the market will start going up again.
SPY Charts
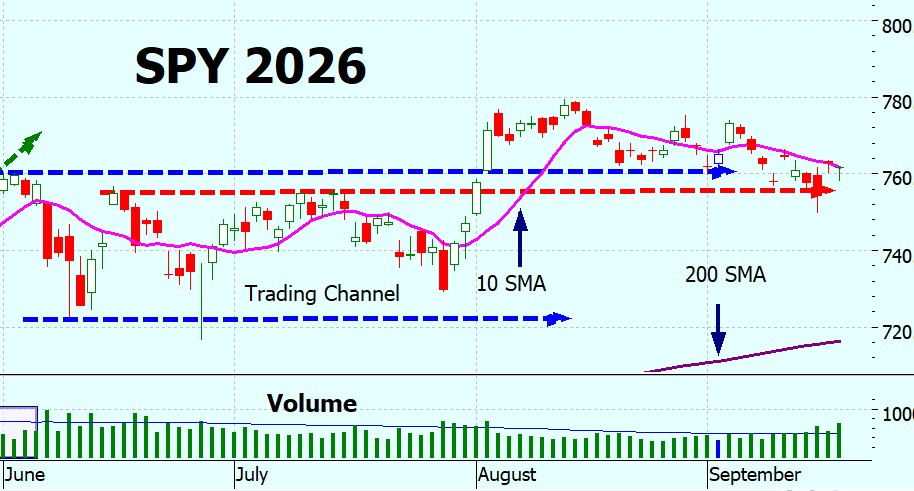
SPY still in a consolidation phase – it really doesn’t know which way it wants to go. I’ve drawn in another line (I am an inveterate line-drawer), the red one which shows that the highs (not all-time highs) in June and July seem to be acting as support. For now, anyway. We’re still more than $40 from a death cross, so an OUT signal doesn’t seem imminent.
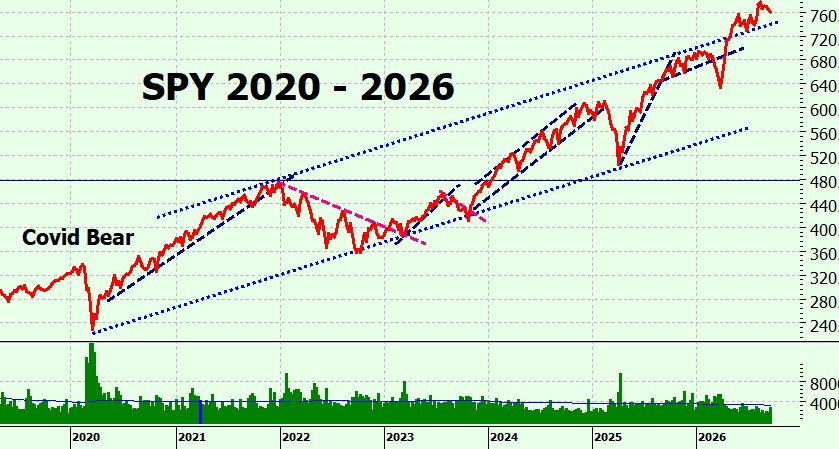
Longer term, the uptrend is holding.
SPYG Charts
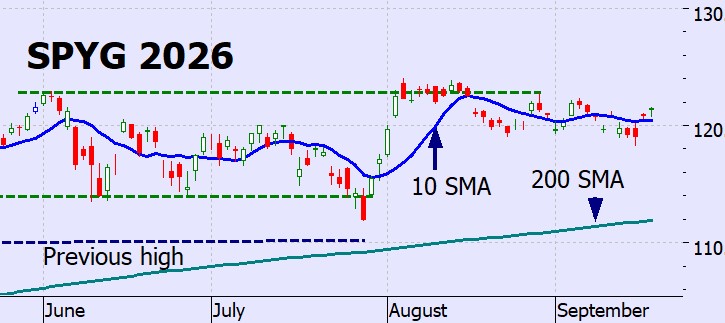
SPYG is also in the holding pattern, also some way off a death cross. The range is getting noticeably tighter, and conventional wisdom says that the tighter it becomes the more decisive the eventual breakout is likely to be.
Which way? We don’t know. Maybe I am just the eternal optimist, but I think it will be up.
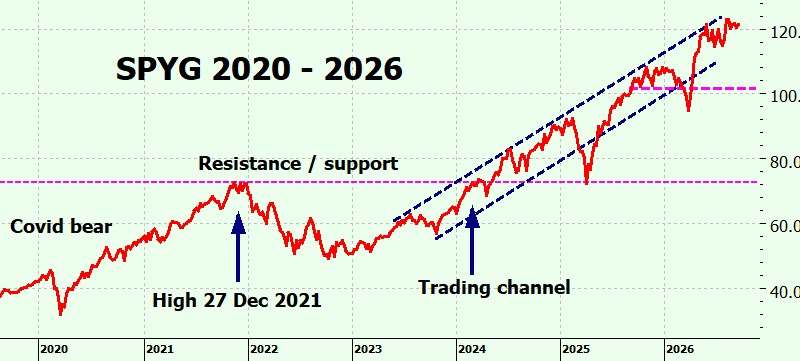
Longer term no surprises. Still in its trading channel.
QQQ Charts
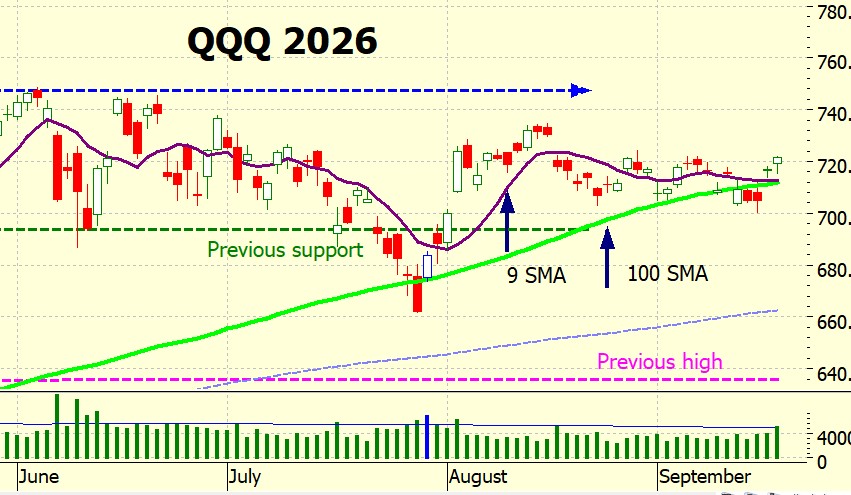
We’ve been watching QQQ in case there is an OUT signal (the death cross) – and I warned last week to wait and see if it did actually cross, not just ‘kiss’ and bounce off. Well, It hasn’t crossed just yet so ITM is still in the trade.
The ITM Plan says that the cross is not confirmed until there is sufficient ‘white space’ between the 9-day and 200-day SMAs. How will you know what is sufficient? The new White Space Checker of course! Just in time!
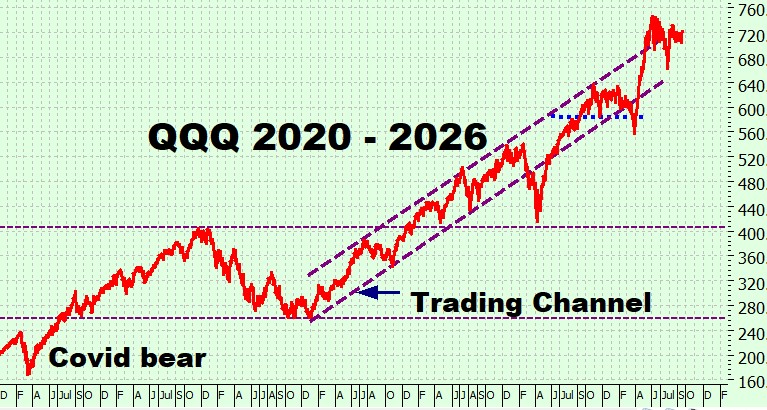
Longer term, it is still hanging around the upper bound of the trading channel.
VIX Chart (Volatility)
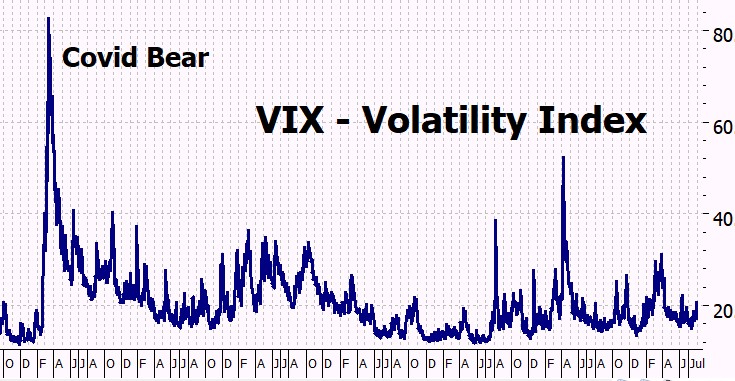
The VIX seems unperturbed about everything.
ITMeter
The week ahead . . .
The economic calendar is fairly light, but Federal Reserve officials will be out in force following last week’s interest-rate rise, although I have noticed that they are less garrulous than they have been in the past. I think the new chairman has clamped down on some of the attention-seeking – just my observation, not necessarily fact.
Wednesday brings the first look at September business activity, while housing and manufacturing data dominate the end of the week. The main earnings include AutoZone, Cintas and Costco.
Monday 21 September Announcements: No major economic announcements; Chicago Fed President Austan Goolsbee speaks.
Tuesday 22 September Announcements: Fed officials John Williams, Philip Jefferson and Thomas Barkin speak.
Wednesday 23 September Announcements: S&P Global flash manufacturing and services PMIs; Fed Governor Michael Barr speaks.
Thursday 24 September Announcements: Weekly jobless claims, new home sales; Fed officials John Williams, Beth Hammack and Anna Paulson speak.
Friday 25 September Announcements: Durable goods orders; final University of Michigan Consumer Sentiment Index; Fed officials John Williams and Beth Hammack speak.
Friday’s durable goods and consumer sentiment reports are the week’s main economic releases. However, with numerous Fed officials speaking throughout the week, markets will also be listening closely for any clues about what comes next for interest rates. Don’t you just wish they would shut up?
The futures . .
The futures are looking reasonably happy right now – but 11 hours to market open.
Next week . . .
Well, I haven’t actually thought about it yet! I gave myself a deadline of this week for AskITM, the calculators, the new front page, the Replication Pack, revising other pages – so I have barely lifted my head. Updating the book I have just finished updating – again – will be a priority, as it now needs links to all the new features. And I still have several other things in the pipeline.
Please try out AskITM and the new calculators – and please let me know about any bugs in the comments below.
Going to treat myself to a massage to celebrate meeting my own deadline!
Hi Heather,
I have been following your ITM methodology with SPY for about two years. After reading your lasted book, I decided to try the strategy with QQQ as well. I currently have a QQQ position with 25 DTE. The death cross is getting very close , but it has not yet confirmed because there isn’t sufficient white space. My question is: since I’m still within the ITM time window for rolling, would you roll the position out now? I am hesitant to wait too long for the death cross to be confirmed because I don’t want to get caught with only a few days left until expiration. Thank you!
Hi Eric – I am afraid I use AI to help me draft my reply.
Here is AI’s reply:
Thank you for taking the time to examine the pack and reconstruct the model.
Most importantly, your independent calculation reproduced the published results exactly:
* Base Model: $162,184.303089
* Turbo Model: $419,719.471924
* All signals, trades and roll counts matched
That was the principal purpose of publishing the pack, so I am pleased that the model could be rebuilt successfully from the stated rules and raw data.
You have identified three points that I will correct:
1. The next-day roll formulas should be applied consistently to all data rows, even though the unused earlier formulas do not affect the published results.
2. Two document footers still show Version 0.1.
3. The phrase “no optimisation” is incorrect. The published rules were applied without discretion throughout the backtest, but the original parameters were selected after testing alternatives. I will amend the wording to make that distinction clear.
A few clarifications:
* The v1.1 change log does record the former and revised results: Base changed from $161,735.32 to $162,184.30, and Turbo from $421,330.26 to $419,719.47.
* The Evidence Register documents the $32,227 total-return comparator calculation.
* The pack expressly states that it uses a synthetic option-value model rather than historical option quotations.
* It also states that expiry dates, historical spreads, commissions, slippage and expiry-based roll-outs are not modelled.
* The independent replication report is described as a computational reconstruction, not unaffiliated third-party verification.
Your cost scenarios are interesting, but—as you acknowledge—the assumed carrying cost and spread are illustrative rather than derived from historical SPY option quotations. They therefore show how the model responds to those particular assumptions, not what the historical result would actually have been after real trading costs.
Thank you again. This is precisely why I published the formulas, data and rules: so that genuine errors could be identified, the calculations could be challenged, and the limitations could be discussed openly. From my AI to your AI – well, this is the future I guess!
Over and out.
h
I love this ! Especially the Bear side ! I just figured I would go back and reread that section if and when we get there . I know you mentioned something about midterms and myths around them and the markets, maybe you can sneak some of that in next week

5 Responses
Thank you for all you do Heather!!!
Hi Heather,
I have been following your ITM methodology with SPY for about two years. After reading your lasted book, I decided to try the strategy with QQQ as well. I currently have a QQQ position with 25 DTE. The death cross is getting very close , but it has not yet confirmed because there isn’t sufficient white space. My question is: since I’m still within the ITM time window for rolling, would you roll the position out now? I am hesitant to wait too long for the death cross to be confirmed because I don’t want to get caught with only a few days left until expiration. Thank you!
Hello Heather, all this AI stuff is making me so lazy and somewhat brain dead. I took your replication zip file pack and uploaded it directly to Claude.
Here is what it came back with:-
https://claude.ai/share/069459e7-77a2-4dce-b981-9bfe6f82c7aa
And here is the code:-
https://claude.ai/public/artifacts/de6a938f-55dd-460c-99c2-9f133c59e65d
I’m getting a little worried that I’m becoming addicted to Claude.
Now to the new calculators!!
Hi Eric – I am afraid I use AI to help me draft my reply.
Here is AI’s reply:
Thank you for taking the time to examine the pack and reconstruct the model.
Most importantly, your independent calculation reproduced the published results exactly:
* Base Model: $162,184.303089
* Turbo Model: $419,719.471924
* All signals, trades and roll counts matched
That was the principal purpose of publishing the pack, so I am pleased that the model could be rebuilt successfully from the stated rules and raw data.
You have identified three points that I will correct:
1. The next-day roll formulas should be applied consistently to all data rows, even though the unused earlier formulas do not affect the published results.
2. Two document footers still show Version 0.1.
3. The phrase “no optimisation” is incorrect. The published rules were applied without discretion throughout the backtest, but the original parameters were selected after testing alternatives. I will amend the wording to make that distinction clear.
A few clarifications:
* The v1.1 change log does record the former and revised results: Base changed from $161,735.32 to $162,184.30, and Turbo from $421,330.26 to $419,719.47.
* The Evidence Register documents the $32,227 total-return comparator calculation.
* The pack expressly states that it uses a synthetic option-value model rather than historical option quotations.
* It also states that expiry dates, historical spreads, commissions, slippage and expiry-based roll-outs are not modelled.
* The independent replication report is described as a computational reconstruction, not unaffiliated third-party verification.
Your cost scenarios are interesting, but—as you acknowledge—the assumed carrying cost and spread are illustrative rather than derived from historical SPY option quotations. They therefore show how the model responds to those particular assumptions, not what the historical result would actually have been after real trading costs.
Thank you again. This is precisely why I published the formulas, data and rules: so that genuine errors could be identified, the calculations could be challenged, and the limitations could be discussed openly.
From my AI to your AI – well, this is the future I guess!
Over and out.
h
I love this ! Especially the Bear side ! I just figured I would go back and reread that section if and when we get there . I know you mentioned something about midterms and myths around them and the markets, maybe you can sneak some of that in next week
Thx always